Tuesday, October 10, 2017

A prime challenge in M&A: Retaining the clients

Acquiring another practice can seem like a sure and quick (if expensive) way to grow a book of business. Practitioners warn, however, that such a move can come with problems. For one: How many of those new clients will stick around?
“If you pay too much up front and don’t retain the clients, you’ve wasted money,” said Scott Kadrlik, a CPA at Meuwissen, Flygare, Kadrlik and Associates in Eden Prairie, Minn.
Clients and individual tax pros also cement bonds over many filing seasons. “If the acquiring firm doesn’t consider these personal ties and provide a comparable culture for client interaction, there’s a real danger that the clients won’t be happy and will go elsewhere,” said New York-based Enrolled Agent Phyllis Jo Kubey.
“You have to really look at the client base. Also, what are the plans of the owner? Do they want to retire or just not want to run a business any longer?” said Jeffrey Schneider, an EA in Port St. Lucie, Fla. “Having the owner in place, especially if there are no other long-time staff that’s staying on or if it’s close to tax season, is invaluable.”
Slow diminishing?
The demographics of the acquired firm’s clients are of first concern. “If you buy a practice from older, retiring practitioners, their clients are probably similar in age,” Kadrlik said. “There may be some estate tax work, but the client work may slowly diminish as their income declines and their need for your services decline.”
“The biggest danger or risk is the quality of the clients being acquired, which also includes the service that they’re accustomed to receiving,” said Ed Guttenplan, managing partner at Wilkin & Guttenplan in East Brunswick, N.J. His firm asks such questions as:
  • What are the standards of client data and related compliance that were required by the seller?
  • What degree of documentation was necessary in connection with the work provided?
  • What kind of vetting is performed in regards to the integrity of the prospective clients, as part of the client acceptance process?
  • Was the adequacy of internal controls at the client considered?
  • Are there fee disputes, large overdue balances or unusual billing arrangements?
“If all of the above answers are acceptable,” Guttenplan adds, “we examine one final question of great significance: how easily the client relationship will be transitioned to the new firm. This can be dealt with by paying for clients based upon retention, but even under a purchase arrangement with those terms, the purchasing firm doesn’t want to pay for clients that will leave shortly after the retention period.”

Price points
Jeff Gentner, an EA in Amherst, N.Y., has purchased several small tax prep practices – and each time negotiated a share-responsibility purchase agreement.
“The seller agreed to write a letter to their clients, explaining the situation and highly recommending me as their new tax professional,” he says. “This letter included my experience and credentials. I have always felt that getting them to come to me the first time was the responsibility of the seller. Keeping them beyond that first meeting was my responsibility.”
“In all practices, the purchase priced agreed upon was based on the first year’s gross income,” he adds. “This way the seller had an incentive to get the clients to me. This method has proved very successful; each time 5 percent to 85 percent of the clients accepted the change. If you use any other method, you’re simply purchasing a list of potential clients.” All purchase agreements should include a covenant not to compete, he added.
“Did the current owner undercharge based on your rates? If so, you may not keep as many clients as you think when they find out your rates,” added Laurie Ziegler at Sass Accounting, in Saukville, Wis. “And what’s the age of the clients? If there are many seniors, this will play a large role in the retention rate.”
“Do you have the staff to service the new client base? Most firms have enough work [and] are buying other firms for the employees and then culling out the clients from the old firm by raising rates,” Kadrlik said.
Many factors can affect retention and other important aspects of a deal – some of which a preparer can help, and some a preparer can’t. “With all the talk of tax reform and knowing that tax reform is most likely imminent, I’m reluctant to enter into any agreement,” Gentner added.

Monday, October 9, 2017

Treasury lays out plan for loosening dozens of Wall Street rules

The Trump administration on Friday urged the overhaul of key rules underpinning trading in U.S. stock, bond and derivatives markets, calling on regulators to loosen dozens of restrictions imposed on Wall Street after the financial crisis.
The 220-page report written by the Treasury Department lays out a series of recommendations for the Securities and Exchange Commission and the Commodity Futures Trading Commission. Rather than making specific demands, the document is intended to be a road map for the agencies to streamline regulations affecting the largest banks, hedge funds and exchanges.
While some of the changes would require congressional action, most could be accomplished by re-writing regulations. The markets review was spurred by President Donald Trump’s February executive order calling for a broad rethink of financial regulations. Treasury issued a separate report on bank oversight reforms in June, and another on asset managers is set to be released in the coming days.
“The review has identified a wide range of measures that could promote economic growth and vibrant financial markets,” the report said.
Opposition Anticipated
A number of the suggestions in the markets study have long been backed by industry, and groups like the U.S. Chamber of Commerce were quick to praise them. Meanwhile, Democratic lawmakers and investor advocates are expected to oppose many of the recommendations. They’ve been critical of the Republican administration’s attempts to cut Wall Street regulations, especially those enacted in response to the financial crisis.
The administration’s wish list isn’t likely to be granted any time soon. The regulatory process is notoriously slow and neither the SEC nor the CFTC have a full compliment of commissioners.
Treasury’s recommendations included proposed adjustments to rules stemming from two laws that tightened capital markets oversight, the Sarbanes-Oxley Act of 2002 and the Dodd-Frank Act of 2010. Two Trump appointees, SEC Chairman Jay Clayton and CFTC Chairman Chris Giancarlo, will be charged with carrying out many of the proposals.
Both agencies saw their oversight roles expanded by Dodd-Frank, with the CFTC being given responsibility for policing the massive over-the-counter derivatives market. The two chairmen appointed by Trump are aligned with the administration’s goal of dialing back some of those rules.
Clayton told lawmakers in March that he thought Dodd-Frank regulations should be reviewed to determine “whether they are achieving their objectives effectively.” And he has repeatedly said that he wants to stem a two-decade decline in the number of publicly traded U.S. companies -- a subject the Treasury report will address. Giancarlo reached out to the derivatives industry earlier this year for suggestions on how the CFTC could simplify and modernize agency rules that he said can be “unnecessarily complex.”
In particular, the Treasury recommended that the CFTC and SEC work better together, especially in monitoring derivatives markets. The report echoed calls by Giancarlo for a loosening of restrictions around the execution of swaps trades. It also backed an effort by Giancarlo to harmonize swaps data reporting.
“We are pleased to see our perspective incorporated in the final product,” Giancarlo said in a statement.
Craig Phillips, a former BlackRock Inc. executive who was major fundraiser for Hillary Clinton’s presidential campaign, has been leading the Treasury’s regulatory review. He is now a senior adviser to Secretary Steven Mnuchin.

Friday, October 6, 2017

Study finds financial rewards can deter whistleblowers

Monetary awards for fraud whistleblowers may seem like a no-brainer, but a new study has found that offering cash for fraud detection may actually negatively effect individual's motivations.
“When you mention financial incentives to potential whistleblowers, you change the decision frame from ‘doing the right thing’ to that of a cost-benefit analysis,” stated James Wainberg, assistant professor of accounting at Florida Atlantic University’s College of Business and one of the study's authors. “As a result, when the perceived risks of reporting are greater than the potential rewards, people will be much less likely to report frauds than had they not been told about the existence of an incentive program to begin with.”
Wainberg co-authored the study, recently published in Auditing: A Journal of Practice & Theory, with Leslie Berger, assistant professor of accounting at Wilfrid Laurier University, and Stephen Perreault, associate professor at Providence College School of Business.
More and more businesses and regulatory agencies are either currently offering or mulling the option offering monetary rewards for the reporting of unscrupulous behavior, but with a catch -- a minimum amount of fraud. The Securities and Exchange Commission, for instance, will offer rewards only if a minimum of $1 million is recovered.
The study's researchers found this type of parameter of fraud reporting would boost the chances that not all fraud will be reported. In an experiment conducted by the researchers, complete with auditors and accounting professionals as test subjects, it was found that fraud was less likely to be reported when a monetary incentive was available, but the amount of fraud committed was less than a given threshold.
“What’s going on is this hijacking of the moral decision frame by the financial incentives,” Wainberg added. “Once that happens, whether or not to report the fraud will largely become a function of an individual’s perceptions of reward adequacy in light of the perceived risk of reporting. So that’s a caution to regulators, compliance professionals and others in corporate governance who are interested in understanding the strengths and weaknesses of offering financial incentives to whistleblowers."
Fraud minimums were also found to significantly delay reporting until the problem was too big to ignore, in turn minimizing the chances of exposing deceit in the early going.
"The question we need to ask is do we really want to incentivize whistleblowers to delay reporting frauds in order to maximize their rewards?" Wainberg concluded.

Thursday, October 5, 2017

Lawmakers question IRS’s $7.25M no-bid contract with Equifax

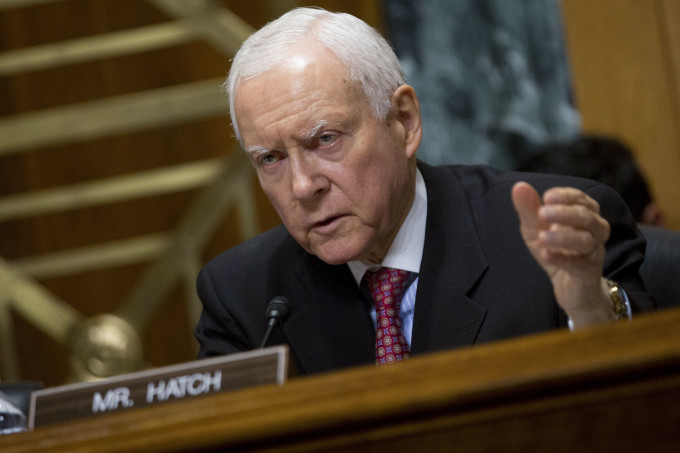
Leaders of the Senate Finance Committee said they were “taken aback” to find out the Internal Revenue Service has recently signed a $7.25 million contract with Equifax for verifying taxpayer identities after the company admitted to a massive data breach exposing the personal information of approximately half of all Americans.
Senate Finance Committee chairman Orrin Hatch, R-Utah, and ranking member Ron Wyden, D-Ore., sent a letter Wednesday to IRS Commissioner John Koskinen asking about why the agency would award a contract to Equifax after the company exposed the private information of more than 145 million Americans. The senators are investigating the impact of the data breach on Americans and federal agencies, and they asked Koskinen to explain the IRS’s rationale for trusting the company to aid with combating identity theft.
“We were taken aback when it came to our attention that last week the IRS awarded Equifax a sole source contract worth over seven million dollars for ‘verify[ing] taxpayer identity and ... assist[ing] in ongoing identity verification and validations needs of the Service,’” they wrote.
They asked Koskinen to help them better understand the IRS’s new and existing contracts with Equifax, and requested information including a copy of the contract and details on the services Equifax will perform. They also wondered, “Why was this awarded as a sole source contract especially in light of the recent breach?” and asked what steps the IRS is taking to ensure that Equifax is protecting taxpayer information. They also asked for a copy of every active contract between the IRS and Equifax, and they want the information no later than Oct. 11, 2017.
Equifax’s former CEO, Richard Smith, who resigned last week amid the outcry over the data breach, testified before Congress Tuesday and blamed an employee for making the error. He repeatedly apologized, however, saying, “As CEO, I was ultimately responsible for what happened on my watch. Equifax was entrusted with Americans’ private data and we let them down.”
Other lawmakers also reacted with shock at the deal, with one of them comparing it to an article on the satirical website the Onion. "It has come to my attention that on September 30th your agency awarded a sole source contract to Equifax to 'verify taxpayer identity' and 'assist in ongoing identity verification and validations,' I was initially under the impression that my staff was sharing a copy of the Onion, until I realized this story was, in fact, true," wrote Rep. Earl Blumenauer, D-Ore., in a separate letter to Koskinen. "As I’m sure you are aware, Equifax is the firm that appears to have been grossly negligent in allowing a massive data hack of the personal information of 145 million Americans. What’s more, this news was public in early September, giving your agency plenty of time to re-evaluate this decision. As a result, I am shocked that the IRS would contract with this firm for activities that they are clearly unfit to carry out."
Rep. Susan DelBene, D-Wash., also sent a letter to Koskinen outlining her concerns. “I write with deep concern over the recently reported decision by the Internal Revenue Service (IRS) to award a no-bid contract to Equifax,” she wrote. “I must question the IRS’ decision to move forward with this contract in light of the ongoing investigations into these incidents, and the general fitness of this company as a federal government contractor to perform functions that are not unrelated to the massive failures outlined above. I request a prompt response on the reasoning behind this decision, as well as a comprehensive explanation of alternatives to this seemingly reckless use of taxpayer dollars.”

Wednesday, October 4, 2017

Excel is about to get smarter

Microsoft Office 2019, set for release by the end of the year, will feature a more powerful Excel that will use artificial intelligence to perform more complex data analysis.

The souped up Excel will be able to understand more about a user’s inputs, and pull information from the internet as needed, TechCrunch reported. For example, users can tag a list as a certain category — such as “company names” — and Excel can get more information about the companies named in that list from Microsoft’s Bing search engine, which will be connected with the spreadsheet. Excel will also be able to discern what category a list might fall under by reading the content of the list.
Also new will be a built-in tool that can create visual representations of the data within an Excel spreadsheet. Dubbed Insights, it is modeled after a similar tool in Microsoft’s Power BI suite. The charts and graphs are manipulable by the user as well.
“Office 2019 will add new user and IT capabilities for customers who aren’t yet ready for the cloud,” said Jared Spataro, Microsoft’s general manager for Office, in a blog post. “For example, new and improved inking features—like pressure sensitivity, tilt effects, and ink replay—will allow you to work more naturally. New formulas and charts will make data analysis for Excel more powerful ... Cloud-powered innovation is a major theme at Ignite this week. But we recognize that moving to the cloud is a journey with many considerations along the way. Office 2019 will be a valuable upgrade for customers who feel that they need to keep some or all of their apps and servers on-premises, and we look forward to sharing more details about the release in the coming months."

Tuesday, October 3, 2017

IMA CEO Jeff Thomson favors accountants over robots

Photo courtesy of Ed Mendlowitz
Institute of Management Accountants president and CEO Jeff Thomson unveiled a new campaign to emphasize the value of management accountants as more jobs fall prey to robots and automation.
During a speech Monday at a meeting of the Accountants Club of America in New York, Thomson discussed how accountants can deal with the threat of automation by learning new skills and technologies to stay on top of the latest trends. He also showed a new advertising campaign for the IMA’s Certified Management Accountant credential in which a robot gives up its seat at a conference room table to accommodate an accountant, telling him, “Sorry, I was just keeping your seat warm.” The commercial can be viewed on YouTube.
Thomson opened his speech by observing a moment of silence for the victims of the mass shooting in Las Vegas outside the Mandalay Bay hotel. The shooter, Stephen Paddock, was later identified as a retired accountant.
During his speech, Thomson cited reports about how job functions would be growing increasingly automated in the future, including in the accounting profession. A Deloitte report, “The robots are coming,” suggested that 56 percent of finance roles have a high probability of automation, and according to the World Economic Forum's Future of Jobs report, 65 percent of children entering primary school are now expected to end up working in roles that currently do not exist.
“We ought to be working with a sense of urgency at the IMA, the AICPA, the New York State Society [of CPAs] and organizations around the world with academia, with partner firms, with companies, to be talking more about that than about these fancy statistics,” said Thomson. “Whether they’re off by an order of magnitude, I could care less.”
He cited a series of articles in recent industry publications including Accounting Today about the impact of increased automation on audit fees, and how CFOs and others in the finance industry may be becoming obsolete or turning into DFOs, or digital finance officers. “There’s a lot going on in terms of impacts on the audit and the automated audit,” said Thomson. “What’s the role of the advisory professional, the human being? Whether it’s woe is me or great new jobs are going to be created, change is difficult, and getting ahead of change is even more difficult. That’s why we need to be talking with a sense of urgency and a call to action about the competencies that we need to develop today, not in the future.”
Thomson also discussed his earlier career at AT&T watching as automation took over the telecommunications industry.
“What can you do to be future proof, or as future proof as possible?” he asked. “Automation is not coming. It’s here now. It will increase quickly. It’s not a bad thing. I would argue that we as advisors, strategic business partners, have responsibilities not only for operational effectiveness, which is part of automation and cost savings, but also for the long-range strategy. That’s just coming to grips with reality. Embrace technology as an opportunity, not just a risk. Develop your skills in data science and data analytics, synthesis and relationship management. Whether it’s Watson or all the smart robots and chatbots, they still only operate within a very, very narrow scope of influence. They have to be programmed. If we draw the line there and say that’s all that’s going to happen, we’re going to be in big trouble. But I think at least for a while, there’s plenty of room for human judgment, human insight and business savvy.”

Monday, October 2, 2017

Winning the coming divergence in accounting

There have always been differences between the biggest firms in accounting and the rest — the 97 or 98 percent of firms that have, say, fewer than 20 people. Both groups serve very different client bases, for instance, using different tools; they recruit employees in different ways and offer very different careers. Yet at bottom, accountants have always all been recognizably of the same tribe, with more similarities than differences, performing work that is — allowing for scale — much the same.
But that may not be the case for long, according to Illinois CPA Society president and CEO Todd Shapiro. A series of technological innovations — from big data, to artificial intelligence and machine learning, to Blockchain and robotic process automation — are in the midst of completely reshaping the services of the largest firms, and the skill sets of their employees. Already, the Big Four are looking to hire more entry-level staff with skills in data analysis, and the expectation is that being savvy in technology will soon be as valuable as more traditional accounting skills (if not more so) in looking for a job at the biggest 3 to 4 percent of firms.
But for the rest? Not so much, according to Shapiro: “If you talk to the 43,400 firms with less than 20 people who service Main Street America, they’re not using Blockchain,” he said. “It’s going to take time. It’s not now, not next year, not in seven years. ... Data analytics aren’t going to be for small businesses in the next seven years.”
And while the Big Four and their like have always adopted new technology more quickly, the major difference here is that the skills required of the accountants using the technology will be different, too, which was not the case before. And that’s going to lead to a major split in accounting over the next five to seven years, Shapiro suggested. “It’s going to be more of a divergent profession than we’ve had in the past,” he said. “Is a small firm going to be using computers to read contracts? Their reconciliations won’t be done by computers. And what if a Big Four person wants to go to a small firm? They’re going to say that a computer does most of those tasks, while the small firm will need someone who can do all those tasks. The small firm will say, ‘I don’t have drones doing inventory.’”
Over the next five to seven years, he suggested, this divergence between the staffing demands at the more tech-forward large firms, and those of the more traditional smaller practices, will lead to two different types of accountants, which will complicate many of the profession’s traditional pathways for the near- and mid-term.
In the long run, though, Shapiro believes that progressive midsized firms will drive a reconvergence, hiring the new kind of accountant from the Big Four, and smaller firms will eventually follow along, driven in no small part by their small-business clients: “Even the corner grocery store 15 years from now will have sold out to younger generations that are more tech-savvy,” he explained. “And those businesses will begin to adopt RPA for inventory, accounting, and so on. So who’s going to take care of those businesses?”
His analysis of the future is compelling, if slightly sobering. But my question is this: Do small firms have to wait? Can’t they start diving into these new technologies and services now?
Yes, the expense currently involved in some of them can be prohibitive — but that won’t always be the case, and there are many tools (in data analysis particularly) that are affordable right now. Why not start building those skill sets and the base of those new service offerings sooner, rather than later? One of the beauties of technology is how it lowers barriers to entry — if you’re willing to try.
The time to win the divergence is now, for firms of all sizes.